Unit 5 · 8 teaching hours · 19 min read
e-Business, e-Commerce and Digital Payments in Nepal
What the syllabus asks for 6
- e-Business and e-Commerce
- The online customer funnel and unit economics
- The payment problem
- Nepal's payment architecture
- Building and running an e-business
- Seeing e-business: funnels, unit economics and netting
You can order a pair of shoes on a phone in Pokhara, pay with a QR code from a bank account in Biratnagar, and have the shoes delivered in a few days.
Three networks cooperated: a marketplace that matched you with a seller, a payment system that moved money between two banks that have never spoken to each other directly, and a logistics network.
This unit separates the business ideas (e-business models, revenue models, metrics) from the plumbing (how Nepal's retail payments are cleared and settled), and then shows how to count, in rupees, whether an online business is healthy.
- e-business versus e-commerce; B2B, B2C, C2C, B2G/G2C, and m-commerce models and revenue models.
- Funnel, conversion, CAC and customer lifetime value calculations.
- Nepal's digital payment architecture: the central bank's role, switches, ConnectIPS, QR payments, wallets and licensing; clearing and multilateral netting with numbers.
5.1 e-Business and e-Commerce
e-Business is the use of the Internet and related technologies to run all the processes of a business: buying, selling, serving customers, collaborating with partners, and internal operations (ERP, e-learning, e-recruitment).
e-Commerce is the narrower part concerned with buying and selling goods and services and the payments that go with them. e-Commerce has stages: pre-sale (search, comparison), the order and payment, delivery, and after-sales service.
Benefits: global reach at low cost, 24-hour service, lower transaction and inventory cost, personalisation, and easy measurement.
Limits in Nepal: uneven connectivity, trust and fraud worries, cash-on-delivery habit, address and logistics challenges, and thin card penetration.
| Model | Parties | Example | Typical revenue |
|---|---|---|---|
| B2C (business to consumer) | Firm sells to individuals | Online shop, ticketing, food delivery | Product margin, delivery fees |
| B2B (business to business) | Firm sells to firm | Wholesale portal, e-procurement | Per-order margin, subscription |
| C2C (consumer to consumer) | Individuals via a platform | Second-hand marketplace (Hamrobazar-type classifieds) | Listing fees, advertising, commission |
| B2G / G2C / G2B | Business or citizen with government | Online tax filing, bill payment, Nagarik App services | Service charges (or none) |
| P2P / social commerce | Users trade through social platforms | Facebook shops, live selling | Often none; platform ads |
| m-commerce | Any of the above on a mobile phone | Wallet shopping, app ordering | As above |
Revenue models: direct sales, commission on transactions, subscription, advertising, listing or membership fees, freemium, affiliate links, and data/analytics services.
A marketplace earns commission but owns no stock; an inventory model takes the stock risk; a dropshipper orders from the supplier after the customer pays.
5.2 The online customer funnel and unit economics
An online business is managed as a funnel: visitors, then add-to-cart, then checkout, then payment. Conversion rate = orders ÷ visitors. Suppose 100,000 visitors in a month with step rates 5%, 40% and 70%:
| Funnel stage | Users | Step rate |
|---|---|---|
| Visitors | 100000 | |
| Add to cart | 5,000 | 5% |
| Start checkout | 2,000 | 40% |
| Complete payment | 1,400 | 70% |
The overall conversion is 1.40%, giving 1,400 orders. Improving the weakest step is cheapest: raising checkout completion from 70% to 80% adds 200 orders without any extra advertising.
Customer acquisition cost (CAC) = marketing spend ÷ new customers. With Rs 1,50,000 of advertising and 1,400 orders, CAC = Rs 107.14.
If the average order value is Rs 2,400 with 22% gross margin, gross profit per order is Rs 528, so the first order already covers its acquisition cost with Rs 420.86 left over.
Customer lifetime value (LTV) = gross profit per order × orders per year ÷ annual churn. With 3 orders a year and 25% churn (expected life 4 years), LTV = 528 × 3 / 0.25 = Rs 6,336, and LTV/CAC = 59.1.
A ratio above 3 is generally healthy; this one is implausibly high, which tells the analyst that the sample is too small or that the CAC ignores returns, delivery cost and discounts.
The usefulness of the metric is in knowing which assumption to challenge.
5.3 The payment problem
Buying online needs a way for money to move between the buyer's account and the seller's. In cash-based economies this is the hardest part of e-commerce.
Payment instruments: cards (debit, credit), bank transfer (account to account), mobile wallets (stored value), QR payments, cash on delivery (COD), and (in some countries) mobile money accounts at telecoms.
Every electronic payment passes through three stages: authorisation (is the payer allowed and funded?), clearing (exchanging the payment instructions among banks) and settlement (the actual movement of funds between the banks' accounts at the central bank).
5.4 Nepal's payment architecture
Specific limits, fees and product names change often; consult the current Nepal Rastra Bank (NRB) circulars and the operators' websites before relying on them.
The regulator and the law
The Nepal Rastra Bank, the central bank, regulates and oversees payments under the Payment and Settlement Act, 2075 (2019) and its by-laws. NRB issues licences and sets rules for risk, customer protection and interoperability.
Two licence families matter in this unit: a Payment System Operator (PSO) runs a payment system (a switch, a clearing house, or a QR network connecting many institutions); a Payment Service Provider (PSP) offers payment services to customers, such as a mobile wallet or a prepaid card.
Banks and financial institutions, licensed by NRB, issue accounts and cards. The settlement of final balances happens in the banks' accounts held at NRB, which is why central-bank money is the "settlement asset".
The main infrastructure pieces
| Component | Operator and role |
|---|---|
| Nepal Clearing House Limited (NCHL) | A PSO owned by banks and institutions. Runs the National Payment Interface (NPI) for interoperable transfers, ConnectIPS (account-to-account credit transfers for bills, remittance, salaries and e-commerce, in which the customer authorises a debit from their bank account in a bank-neutral web or mobile flow), and cheque clearing (ECC); also NepalPay QR, a QR scheme |
| Fonepay | A PSO that operates a switch connecting banks' accounts and cards with merchants' Fonepay QR codes and ATM/POS networks; most merchants display one |
| Wallets (PSPs) such as eSewa, Khalti, IME Pay | Hold the user's stored value; pay merchants, bills and top-ups; the user loads money from a bank account (often through ConnectIPS) |
| Card networks and bank switches | Domestic cards processed by bank switches; international cards connect through global networks |
| Banks and NRB | Hold customer accounts and, for final settlement, the banks' accounts at NRB |
Operationally, the flow of a QR payment is: (1) the merchant displays a static or dynamic QR code with an identifier; (2) the customer scans it in a bank or wallet app; (3) the app sends an authorisation request through the switch to the customer's bank or wallet; (4) the debit is made and the merchant's bank or wallet is notified; (5) the switch records the obligation and (6) net positions between institutions are settled periodically at the central bank.
Wallet balances are backed by funds that the PSP must hold in a settlement or escrow account at a bank; the customer's wallet balance is a claim on that bank-held pool.
Customers' eKYC (identity verification) and limits per transaction and per month are set by NRB's rules.
Clearing by multilateral netting: a worked example
If every payment between banks were settled one by one, the volume of settlement transfers would be huge. Switches therefore net obligations: each bank pays or receives only the net of everything it owes and is owed.
Below is an invented day's obligations among four banks (rupees in crore; row = payer, column = receiver):
| From \ To | A | B | C | D | Total sent |
|---|---|---|---|---|---|
| A | 0 | 120 | 80 | 60 | 260 |
| B | 90 | 0 | 50 | 100 | 240 |
| C | 110 | 70 | 0 | 40 | 220 |
| D | 30 | 130 | 90 | 0 | 250 |
| Total received | 230 | 320 | 220 | 200 | 970 |
Each bank's net position is received minus sent. The positions always sum to zero (money is only moved, never created).
| Bank | Sent | Received | Net position | Settles |
|---|---|---|---|---|
| A | 260 | 230 | -30 | pays |
| B | 240 | 320 | +80 | receives |
| C | 220 | 220 | +0 | — |
| D | 250 | 200 | -50 | pays |
Gross obligations total 970 crore, but only 80 crore must actually move (the sum of the positive net positions): a saving of 91.8%.
Netting only between pairs (bilateral) would still require 190 crore of transfers, so multilateral netting through a central switch is more efficient.
The risk side: a bank that cannot pay its net debit on settlement breaks the whole cycle, so participants pre-fund collateral or have limits ("settlement risk").
Why it matters for an e-business
A merchant choosing payment options is choosing fees, settlement time (T+0, T+1), refund process, chargeback or dispute handling, and the risk of fraud.
Typical integration: the merchant's website redirects the buyer to a payment gateway (a PSP such as a wallet or the bank's page), the gateway returns a success/failure callback, and the merchant's server verifies the transaction by calling the gateway's lookup API before delivering the goods (never trust the browser redirect alone).
Unit 6 covers the controls around this.
5.5 Building and running an e-business
An online business needs: a platform (own site with a CMS or shop framework, or a marketplace seller account), a catalogue, a payment gateway, logistics (own riders or courier partners, with Nepal-specific issues such as incomplete street addresses and COD returns), customer service, analytics (funnel, abandoned carts) and legal compliance (company registration, VAT, consumer protection, the Electronic Transactions Act 2063).
Typical pitfalls: underestimating delivery and returns costs, running promotions that destroy margin, and ignoring mobile-first design when most users arrive by phone.
5.6 Seeing e-business: funnels, unit economics and netting
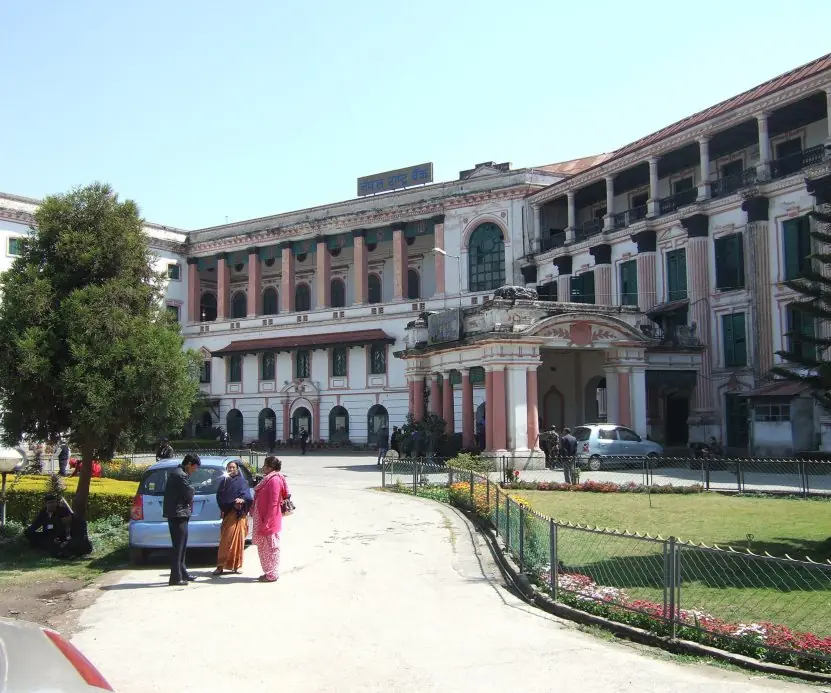
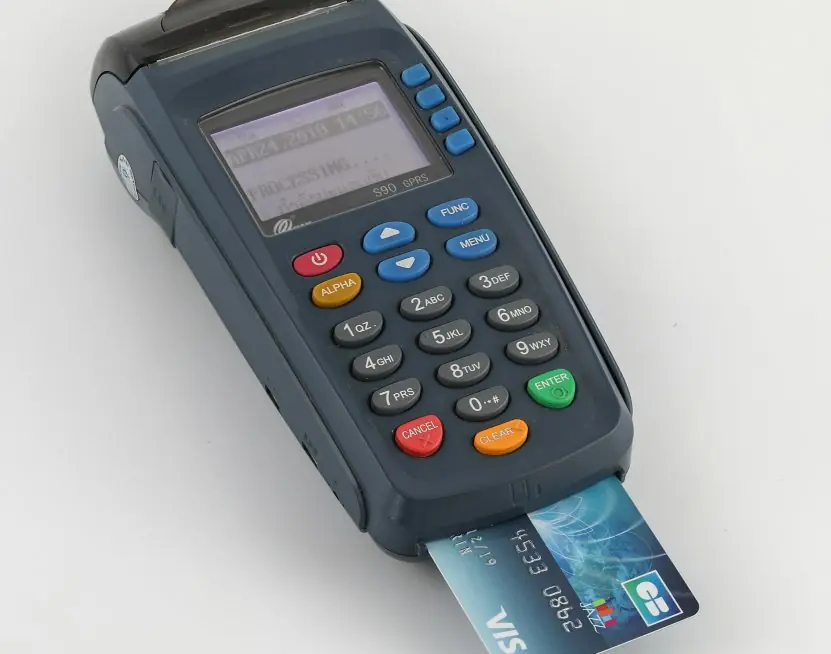
An online business lives on small percentages and thin margins, and Nepal's payment system relies on netting. The plate shows the regulator's home and the funnel of a typical shop, and the figures show the unit economics and the settlement arithmetic.



5.6.1 Eight advantages of e-business for Nepali firms
- Wider market. An online shop is open to customers across Nepal and abroad, not only to those who pass the building. A Bhaktapur handicraft seller can sell to tourists who returned home. The market grows without new shops.
- Lower operating cost. There is no need for prime shop space or many counter staff, and orders are processed by software. A small firm can start with a laptop and a phone. Savings can be passed on as lower prices.
- Open all day. Customers order at midnight or on a holiday. Migrant workers abroad send gifts and recharge at their own time zone. Sales no longer stop when the shutter closes.
- Faster transactions. Payment by wallet, ConnectIPS or QR completes in seconds and creates a digital record. Cash handling, queues and counting errors fall. A utility company that accepts online payment collects bills faster.
- Better customer data. Each visit and order produces data on what people want. The shop can personalise offers and measure funnel steps as in Figure 5.1. Decisions are based on evidence, not guesses.
- Direct relationship. Producers can sell directly to buyers, cutting layers of middlemen. A farmer cooperative can list vegetables and take orders from restaurants. The producer earns more and the buyer pays less.
- Easy scaling. A system built for 100 orders a day can be upgraded to handle 10,000 with more servers. Cloud services are rented by use. A festival-season rush does not require permanent staff.
- Better service and tracking. Customers see order status, receipts and delivery tracking, and can complain by chat. Fast replies create trust. Reliable service is the main reason people return to an online shop.
Chapter summary
- e-Business covers all online business processes; e-commerce is online trade; models include B2C, B2B, C2C, G2C and m-commerce with revenue by margin, commission, subscription or advertising.
- Funnel metrics, CAC and LTV tell whether growth is profitable; sanity-check the assumptions.
- A payment passes through authorisation, clearing and settlement; NRB licenses PSOs and PSPs under the Payment and Settlement Act 2075.
- NCHL (NPI, ConnectIPS), Fonepay (switch and QR), wallets and banks form the retail payment network; multilateral netting reduces settlement transfers.
- Always verify payment status server-side with the gateway before fulfilment.
Practice
- Differentiate e-business from e-commerce.
- Classify:abuying a train-style ticket online,ba wholesaler's ordering portal for shops,cselling a used phone on a classifieds site,dpaying electricity bills online.
- For 80,000 visitors with rates 4%, 50% and 80%, compute the number of orders and the conversion rate.
- CAC is Rs 200 and LTV Rs 900. What is LTV/CAC? Is it healthy?
- Explain authorisation, clearing and settlement.
- What is the difference between a PSO and a PSP? Give one example of each from this chapter.
- In the netting example, which banks pay, which receive, and how much moves?
- Why must a merchant verify payment server-side?
- Why does a wallet need an escrow or settlement account at a bank?
- List four risks specific to selling online in Nepal.
Answers and worked solutions
1. e-business: all business processes online (including internal ones). e-commerce: buying and selling online.
2.(a) B2C;(b) B2B;(c) C2C;(d) G2C/B2G (citizen-to-government payment) or B2C if the utility is a company.
3. 80,000 × 0.04 = 3,200; × 0.5 = 1,600; × 0.8 = 1,280 orders; conversion 1,280/80,000 = 1.6%.
4. 900 / 200 = 4.5, above the common threshold of 3: healthy, subject to the assumptions behind LTV.
5. Authorisation: check the payer and funds. Clearing: exchange and reconcile payment instructions between institutions. Settlement: move final funds between banks' accounts at the central bank.
6. PSO operates a payment system (NCHL, Fonepay); PSP offers customer-facing services such as a wallet (eSewa, Khalti).
7. Net positions (crore): see the table; positive banks receive and negative banks pay, and the total moved is 80 crore.
8. A browser redirect can be forged or interrupted; only a server-to-server lookup proves the payment really succeeded.
9. Wallet balances are claims on real money; the escrow account protects customers' funds from the PSP's own creditors and risks.
10. Fraud and chargebacks, COD return costs, address and delivery problems, connectivity limits and low trust in online payments.
Model answers: medium (5 marks) and long (10 marks) questions
Q1 (5 marks). An online shop gets 100,000 visitors; 5 percent add to cart, 40 percent of those start checkout and 70 percent of those pay. Advertising cost is Rs 1,50,000 and the average order is Rs 2,400 with 22 percent gross margin. Find conversion, CAC and profit per order.
Introduction. An online business is managed with funnel and unit-economics measures (section 5.2, Figure 5.1).
- Funnel. 100,000 x 0.05 = 5,000 add to cart; 5,000 x 0.40 = 2,000 start checkout; 2,000 x 0.70 = 1,400 orders.
- Conversion rate. Orders / visitors = 1,400 / 100,000 = 1.40 percent.
- CAC. Marketing spend / new customers = 1,50,000 / 1,400 = Rs 107.14.
- Gross profit per order. 2,400 x 0.22 = Rs 528.
- First-order result. 528 - 107.14 = Rs 420.86 left after acquisition.
- Improvement. Raising checkout completion from 70 to 80 percent gives 2,000 x 0.80 = 1,600 orders, 200 more, without extra advertising.
| Stage | Users | Step rate |
|---|---|---|
| Visitors | 100,000 | |
| Add to cart | 5,000 | 5% |
| Checkout | 2,000 | 40% |
| Paid | 1,400 | 70% |
Conclusion. The shop makes a positive profit on the first order; improving the weakest funnel step is the cheapest growth.
Q2 (5 marks). Explain multilateral netting with the four-bank example (net positions A -30, B +80, C 0, D -50) and state its advantage.
Introduction. Banks owe each other many payments during a day; netting reduces them to one net settlement per bank (section 5.4, Figure 5.2).
- Gross obligations. Each bank sends payments to the others; in the example the total is Rs 970 crore.
- Net position. For each bank, received minus sent: A 230 - 260 = -30; B 320 - 240 = +80; C 220 - 220 = 0; D 200 - 250 = -50.
- Check. -30 + 80 + 0 - 50 = 0, because money is moved and not created.
- Settlement. Banks with negative positions pay the central bank or settlement agent: A pays 30 and D pays 50; B receives 80.
- Saving. Only Rs 80 crore moves instead of 970, a saving of 91.8 percent; bilateral netting would still need 190 crore.
- Risk. The liquidity needed is much smaller, but a bank that cannot pay its net amount affects all, so limits and collateral are used.
Conclusion. Multilateral netting through a central switch minimises transfers and liquidity and is the basis of retail payment clearing.
Q3 (10 marks). Define e-business and e-commerce. Explain the business models, the payment system architecture in Nepal and the security and legal issues of e-commerce.
Introduction. E-business is the use of the Internet and information systems to run all business activities, such as buying, selling, producing and serving customers. E-commerce is the part that deals with buying and selling online.
For Nepal the topic joins technology, payment regulation and law (sections 5.1 to 5.5, Figures 5.1 to 5.3).
- E-business versus e-commerce. E-commerce is the transaction part (online shop); e-business also covers internal processes (ERP), supply chain and customer service.
- Business models. B2C (Daraz to consumers), B2B (wholesaler to retailer), C2C (marketplace between individuals), G2C (government to citizens, as in the Nagarik App) and G2B (tax and customs portals).
- Revenue models. Sales margin, commission, advertising, subscription and transaction fees.
- Payment methods. Cash on delivery, cards, wallets, bank transfer through ConnectIPS and QR payments.
- Architecture. The customer's app, a payment service provider or switch, the banks and the central bank. The switch routes and authorises instantly; the final settlement is netted and done through the central bank.
- Regulation. Nepal Rastra Bank licenses payment service providers and operators under the Payment and Settlement Act, 2075 (2019); the Electronic Transactions Act, 2063 (2008) gives legal validity to electronic records and signatures.
- Security. HTTPS with TLS, strong authentication (MFA), tokenisation of card data, fraud monitoring and secure storage of passwords as salted slow hashes.
- Challenges. Trust, last-mile delivery, address problems, low digital literacy, internet access and refund handling.
| Model | Seller | Buyer | Nepali example |
|---|---|---|---|
| B2C | Business | Consumer | Online shop |
| B2B | Business | Business | Wholesale portal |
| C2C | Consumer | Consumer | Classified marketplace |
| G2C | Government | Citizen | Nagarik App |
Conclusion. E-business extends the firm across the Internet. It succeeds when a sound business model, an efficient payment path, regulation and security work together, so that customers trust paying online.