Unit 5 · 9 teaching hours · 21 min read
Market Structure
What the syllabus asks for 8
- Market structures compared
- The rule for profit maximisation
- Perfect competition
- Monopoly
- Monopolistic competition
- Oligopoly
- Seeing the market structures: price taker, monopolist, discriminator, oligopolist
- Eight lessons from market structures for Nepali firms and consumers
How a firm sets price and output depends on how many competitors it has and how similar their products are. This unit finds equilibrium under perfect competition, monopoly, monopolistic competition and oligopoly, using the cost and revenue curves of Unit 4.
- The profit-maximisation rule: MC = MR (and the TR–TC view).
- Perfect competition: short- and long-run equilibrium, supply curves.
- Monopoly: equilibrium, price discrimination. Monopolistic competition. Oligopoly and cartel pricing.
- Worked numbers for each structure.
5.1 Market structures compared
| Feature | Perfect competition | Monopoly | Monopolistic competition | Oligopoly |
|---|---|---|---|---|
| Number of sellers | very many | one | many | few |
| Product | identical | unique, no close substitute | differentiated | identical or differentiated |
| Entry | free | blocked | free | difficult |
| Price control | none (price taker) | considerable (price maker) | some | considerable, interdependent |
| Demand curve faced | horizontal | downward (market demand) | downward, fairly elastic | kinked or indeterminate |
| Examples | farm produce markets | electricity distribution, a patented drug | restaurants, clothing, mobile apps | telecom, airlines, cement |
5.2 The rule for profit maximisation
Profit = TR − TC. A firm increases output while an extra unit adds more to revenue than to cost, and stops when it adds equally: MR = MC, with MC rising through MR (second-order condition: the MC curve cuts MR from below).
The same result in the TR–TC approach: output where the vertical gap TR − TC is greatest (the slopes of TR and TC are equal).
5.3 Perfect competition
Characteristics: many buyers and sellers (each too small to affect price), homogeneous product, free entry and exit, perfect knowledge, perfect mobility of resources. The firm takes the market price P: AR = MR = P, so equilibrium is where P = MC with MC rising.
Short-run equilibrium. The firm may earn supernormal profit (P > AC), normal profit (P = AC, the break-even point), or a loss (P < AC).
It continues to produce as long as P ≥ minimum AVC, because then it covers variable costs and part of fixed cost; below minimum AVC (the shutdown point) it closes, losing only its fixed cost.
P = 60: P = MC at Q = 5 (MC = 60). TR = 300, TC = 320 → loss of 20; the loss is less than the fixed cost (100) and P (60) exceeds AVC (44), so the firm keeps producing (shutting down would lose 100).
P = 80: P = MC at Q = 6; TR = 480, TC = 400 → profit of 80. P = 40: MC = 40 at Q = 3 or 4 where AVC is at its minimum (40): the shutdown point; below 40 the firm produces nothing.
Firm's short-run supply curve is the rising part of its MC curve above minimum AVC; the industry's short-run supply curve is the horizontal sum of all firms' supply curves.
Long-run equilibrium. Supernormal profits attract new firms: supply shifts right, price falls; losses cause exit: price rises.
The process ends when P = AR = MR = SMC = LMC = SAC = LAC (at its minimum): every firm earns normal (zero economic) profit, produces at the lowest-cost scale (productive efficiency, P = MC allocative efficiency).
The long-run industry supply curve is horizontal for a constant-cost industry, upward for an increasing-cost industry (input prices rise as industry grows), downward for a decreasing-cost one.
5.4 Monopoly
A monopolist is the only seller. Sources: control of a key resource, patents and copyrights, legal licence (public utilities), economies of scale (natural monopoly), or deliberate barriers.
The firm is the industry, faces the downward-sloping market demand (AR), so MR < AR. Equilibrium: MR = MC with MC cutting MR from below; price is read from the demand curve (AR) at that output, not from MC, so P > MC.
Short run: may earn supernormal profit, normal profit or a loss (but must cover AVC). Long run: because entry is blocked, supernormal profit can persist; it adjusts its plant to the profit-maximising scale. A monopolist never produces on the inelastic part of demand.
Demand P = 100 − Q; total cost TC = 500 + 20Q, so MC = 20; MR = 100 − 2Q. Monopoly: MR = MC → 100 − 2Q = 20 → Q = 40, P = 100 − 40 = 60. TR = 2,400; TC = 500 + 800 = 1,300; profit = 1,100.
Perfect competition (P = MC): P = 20, Q = 80; price is lower and output twice as large. Deadweight loss of monopoly = ½ × (P − MC) × (Q_competitive − Q_monopoly) = ½ × 40 × 40 = 800: transactions that buyers value above cost are lost.
Hence regulation: price caps, antitrust law, public ownership, or regulated pricing of natural monopolies.
Price discrimination
Charging different prices for the same good to different buyers not based on cost differences.
Conditions: market power, ability to separate markets (by age, place, time, income), no resale between them (arbitrage), and different demand elasticities.
Degrees: first degree (perfect discrimination: each buyer charged the maximum they would pay; the monopolist captures all consumer surplus), second degree (price by quantity: block tariffs for electricity, bulk discounts), third degree (by market segment: student/senior tickets, domestic vs foreign tourist fees, peak/off-peak rates).
In third-degree discrimination set MR₁ = MR₂ = MC: charge the higher price in the less elastic market.
Market 1: P₁ = 100 − Q₁ (MR₁ = 100 − 2Q₁); market 2: P₂ = 60 − Q₂ (MR₂ = 60 − 2Q₂); MC = 20 constant. Set MR = MC in each: Q₁ = 40, P₁ = 60; Q₂ = 20, P₂ = 40. Profit = (60 − 20) × 40 + (40 − 20) × 20 = 1,600 + 400 = 2,000.
Single price: the combined demand for P ≤ 60 is Q = 160 − 2P → P = 80 − Q/2, MR = 80 − Q = 20 → Q = 60, P = 50; profit = (50 − 20) × 60 = 1,800 < 2,000.
Discrimination raises profit, charging more in the less elastic market (market 1).
5.5 Monopolistic competition
Many sellers, differentiated products (brand, quality, location, packaging), free entry and exit.
Each firm has some monopoly power over its own brand, so faces a downward-sloping but fairly elastic demand curve with MR below it; it spends on selling expenses (advertising) and product variation to shift demand.
Short run: like monopoly: MR = MC gives price above MC and possible supernormal profit or loss.
Long run: free entry competes the profit away: each firm's demand curve shifts left and becomes more elastic until it is tangent to its LAC curve at the output where MR = MC: P = AC, zero economic profit.
The tangency lies on the falling part of LAC, so the firm produces less than the minimum-cost output: excess capacity, and P > MC. This is the price of variety.
With product variation and selling costs, the firm chooses the quality and advertising level at which extra revenue equals extra cost; selling costs are a part of AC, shifting the AC curve up while raising demand.
5.6 Oligopoly
A few large firms, so each firm's price and output decisions depend on rivals' reactions (interdependence). Features: barriers to entry, price rigidity, non-price competition (advertising, quality), possible collusion.
No single equilibrium theory exists; models include:
- Kinked demand curve: if a firm raises its price rivals do not follow (it loses many customers: elastic above the kink), but if it cuts its price rivals follow (little gain: inelastic below), so there is a kink at the current price and a gap in MR; MC can change within the gap without changing price: price rigidity.
- Cournot and Bertrand duopoly models (quantity and price competition) and game theory (the prisoner's dilemma: each firm gains by cheating on a collusive agreement, but both lose when both cheat).
- Cartel (collusive) pricing: firms agree to act as a single monopoly to maximise joint profit: set MR_industry = MC and divide output by agreed quotas (OPEC is the standard example).
Two identical firms, market demand P = 100 − Q, MC = 20 (no fixed cost). Joint profit maximisation: MR = 100 − 2Q = 20 → total Q = 40, P = 60; split equally, each produces 20 and earns (60 − 20) × 20 = 800, joint profit 1,600.
Competing price-takers would drive price to 20 and profit to zero. Instability: if firm A secretly produces 30 while B keeps to 20, Q = 50, P = 50: A earns (50 − 20) × 30 = 900 (up from 800) and B only (50 − 20) × 20 = 600.
Each has an incentive to cheat, and cartels are hard to keep together without enforcement (and are illegal in many countries).
5.7 Seeing the market structures: price taker, monopolist, discriminator, oligopolist


5.8 Eight lessons from market structures for Nepali firms and consumers
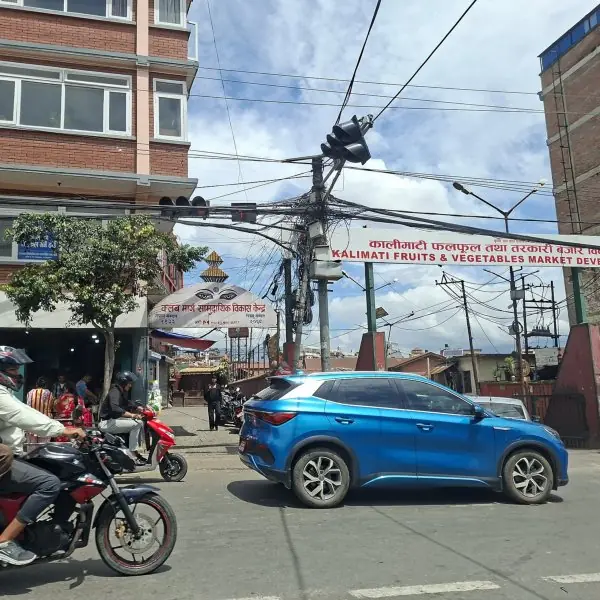
- Competition keeps prices close to cost. In a market with many sellers, such as vegetables at Kalimati, no seller can charge much above the going price. A trader who raises the price loses customers to the next stall. Consumers gain, and sellers earn only a normal profit in the long run.
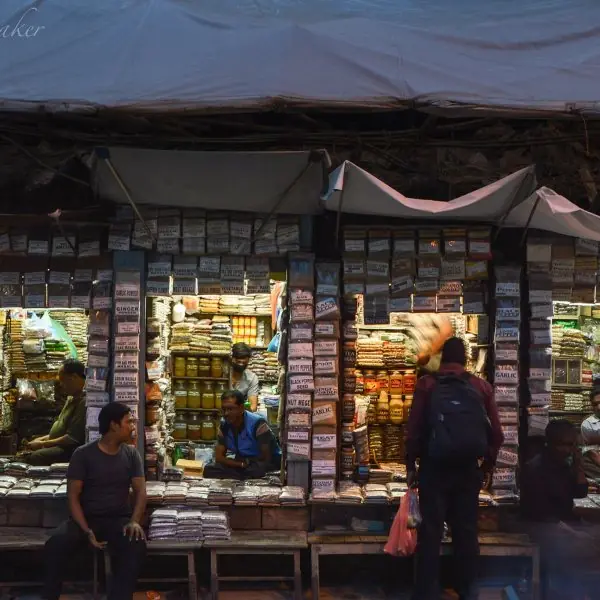
- A monopoly can charge more and produce less. A single seller sets output where MR equals MC and reads a higher price from the demand curve. This is why services such as electricity distribution and water supply are regulated. Without a rule the buyer has no other place to go.
- Natural monopoly needs regulation, not competition. Where one big network is cheaper than two, as in power transmission lines, duplicating the network wastes resources. The state therefore owns it or controls its prices. The aim is to keep the cost advantage and still protect users.
- Price discrimination raises profit and can raise access. Different prices for students, residents and tourists work only if the markets can be separated. Nepal's museum and national-park tickets charge SAARC and foreign visitors more than Nepalis. The seller gains, and low-price groups may get a service they could not otherwise afford.
- Monopolistic competition gives variety at a price. Restaurants, clothing shops and mobile apps sell similar but not identical goods. Each firm advertises to make demand less elastic, and entry of new rivals removes the profit in time. Consumers get choice, but firms run below the lowest-cost scale.
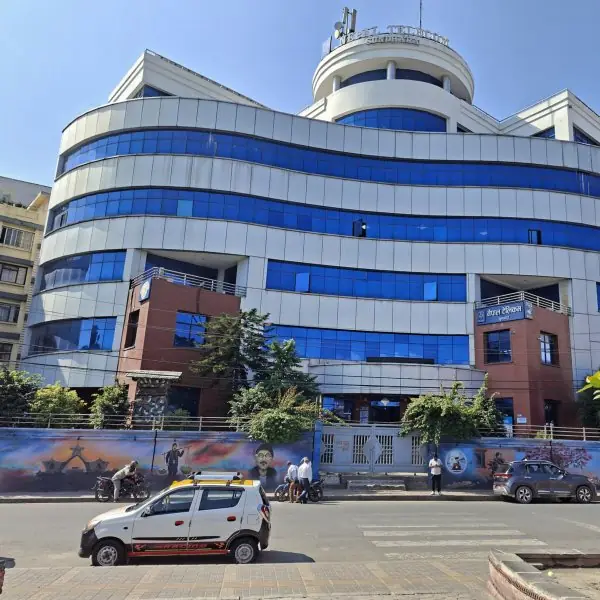
- Oligopolists watch each other. In mobile services, banking and airlines a price cut by one is copied by the others, so firms prefer non-price competition such as offers and service. Prices stay stable for long periods, which the kinked demand curve explains. A student who reads telecom offers can see this at work.
- Cartels are unstable and often illegal. Firms could earn monopoly profit together, but each gains by cheating on its quota. The pay-off table shows why the agreement breaks down without enforcement. Competition law exists to stop firms from agreeing on prices.
- Entry barriers decide long-run profit. Free entry removes extra profit; blocked entry keeps it. Licences, patents, large capital needs and brand loyalty are the barriers. Anyone planning a business in Nepal should ask first how easy it is for rivals to enter.
Formula and fact sheet
- Maximum profit: MR = MC with MC rising; shutdown if P < min AVC.
- Perfect competition: P = AR = MR; short-run supply = MC above min AVC; long run P = min LAC, zero economic profit.
- Monopoly: MR = MC, price from demand, P > MC; deadweight loss ½(P − MC)ΔQ.
- Price discrimination: MR₁ = MR₂ = MC; higher price where demand is less elastic.
- Monopolistic competition long run: tangency, excess capacity, zero economic profit.
- Oligopoly: interdependence; kinked demand; cartel = monopoly outcome, unstable.
Chapter summary
- Every firm maximises profit where MR = MC; the market structure fixes the shape of MR.
- Competition drives price to the minimum of average cost; monopoly restricts output and raises price, creating deadweight loss; price discrimination raises monopoly profit.
- Monopolistic competition gives variety with excess capacity; oligopolists are interdependent and may collude but are tempted to cheat.
Practice
- List the characteristics of perfect competition. Why is its demand curve horizontal for a firm?
- A competitive firm faces P = 50 with MC = 10 + 2Q. Find its output; if AC at that output is 35, find profit.
- Explain the shutdown point and the firm's short-run supply curve.
- Demand P = 80 − Q, TC = 100 + 20Q. Find the monopolist's output, price and profit, and the competitive output.
- Describe the three degrees of price discrimination with examples.
- Why does monopolistic competition lead to excess capacity?
- Explain the kinked demand curve and why prices are rigid in oligopoly.
- Why do cartels tend to collapse?
Answers and worked solutions
1. Many buyers and sellers, identical product, free entry/exit, perfect knowledge. A single firm is too small to affect the market price, so it can sell any amount at the market price: horizontal demand (AR = MR = P).
2. P = MC: 50 = 10 + 2Q → Q = 20. Profit = (P − AC) × Q = (50 − 35) × 20 = 300.
3. The shutdown point is where P = minimum AVC: below it, revenue does not cover variable cost. The supply curve is the part of MC above minimum AVC.
4. MR = 80 − 2Q = MC = 20 → Q = 30, P = 50; TR = 1,500; TC = 100 + 600 = 700; profit 800. Competitive: P = MC = 20 → Q = 60.
5. First degree: each buyer pays maximum (auction, bespoke consultancy). Second: price by quantity (electricity blocks, bulk discounts). Third: by segment (student fares, foreign tourist fees).
6. Long-run tangency between demand and LAC occurs on the falling part of LAC, so output is below the minimum-cost scale.
7. Rivals match price cuts but not rises, so demand is elastic above and inelastic below the current price; MR has a vertical gap, and cost changes within the gap do not change price.
8. Each member gains by secretly selling more than its quota (the prisoner's dilemma), and monitoring is difficult.
Model answers: medium (5 marks) and long (10 marks) questions
Q1 (5 marks). Explain the short-run equilibrium of a firm under perfect competition. When does it shut down? Use the cost table of Unit 4.
Introduction. In perfect competition there are many sellers of an identical product, entry is free, and each firm is a price-taker. The firm's demand curve is horizontal, so AR = MR = P.
Equilibrium rule. The firm maximises profit where MR = MC, which here is P = MC with MC rising. At that output it may earn supernormal profit (P > AC), normal profit (P = AC) or a loss (P < AC).
Cases with TFC = 100 (Figure 5.1).
| Price | Output where P = MC | TR | TC | Result |
|---|---|---|---|---|
| 80 | 6 | 480 | 400 | profit 80 |
| 60 | 5 | 300 | 320 | loss 20, but P > AVC (44): keep producing |
| 40 | 3 to 4 | 160 | 260 | P = min AVC: shutdown point |
Shutdown rule. If P covers AVC, the firm covers all variable cost and part of fixed cost, so producing loses less than closing (loss 20 instead of 100).
If P falls below minimum AVC, each unit adds more to cost than to revenue and the firm closes, losing only the fixed cost.
Conclusion. The firm's supply curve is the rising part of MC above minimum AVC.
Q2 (5 marks). Compare monopoly with perfect competition. Demand is P = 100 − Q and MC = 20; find the equilibrium in each and the deadweight loss.
Introduction. A monopoly is the single seller of a good with no close substitute. It faces the whole market demand, so MR < AR, and it is a price-maker.
Numerical solution (Figure 5.2). MR = 100 − 2Q.
- Monopoly: MR = MC gives 100 − 2Q = 20, so Q = 40. The price is read from demand: P = 60. With TC = 500 + 20Q, TC = 1,300, TR = 2,400 and profit = 1,100.
- Competition: P = MC gives P = 20 and Q = 80.
- Deadweight loss: ½ × (60 − 20) × (80 − 40) = 800, the value of trades lost.
| Point | Perfect competition | Monopoly |
|---|---|---|
| Sellers | very many | one |
| Entry | free | blocked |
| Demand faced | horizontal | downward |
| Rule | P = MC | MR = MC, so P > MC |
| Output and price | high, low | low, high |
| Long-run profit | normal | can stay supernormal |
Conclusion. The monopolist restricts output to raise price, so societies use price caps, competition law or public ownership.
Q3 (5 marks). What is price discrimination? State its conditions and degrees, and show with an example that it can raise profit.
Introduction. Price discrimination means charging different prices for the same good to different buyers, for reasons not based on cost.
Conditions. (1) The seller has market power. (2) The markets can be separated by age, place, time or income. (3) There is no resale (arbitrage) between them. (4) The markets have different elasticities of demand.
Degrees. First degree: each buyer pays the most he would pay, so the seller takes all consumer surplus. Second degree: price depends on quantity, as in block tariffs for electricity. Third degree: price depends on the segment, as in student and foreign-tourist tickets.
Example (Figure 5.3), MC = 20. Market 1: P = 100 − Q gives MR = 100 − 2Q = 20, so Q = 40 and P = 60. Market 2: P = 60 − Q gives Q = 20 and P = 40. Profit = (60 − 20) × 40 + (40 − 20) × 20 = 1,600 + 400 = 2,000.
With a single price the best result is Q = 60, P = 50 and profit 1,800.
Conclusion. The higher price is charged in the less elastic market, and total profit rises by 200.
Q4 (10 marks). Define oligopoly and explain its features. Describe the kinked demand curve model and the cartel model with a numerical example.
Introduction. Oligopoly is a market with a few large sellers, such as telecom, airlines, banking and cement. Each firm's decision depends on how rivals react, so no single equilibrium theory exists.
Features. (1) Few firms with large market shares. (2) Interdependence of price and output decisions. (3) Barriers to entry: capital, licences, brands. (4) Price rigidity. (5) Non-price competition: advertising, offers, service.
(6) Possible collusion. (7) The product may be identical (cement) or differentiated (mobile plans).
Kinked demand curve (Figure 5.4a). If a firm raises its price, rivals do not follow, so it loses many customers: demand above the present price is elastic.
If it cuts its price, rivals follow, so it gains few customers: demand below is inelastic. The demand curve therefore has a kink at the present price (50, at Q = 50), and the MR curve has a vertical gap (from 40 to 10).
Marginal cost may rise or fall inside the gap, from 20 to 35 in the figure, without changing price or output. This explains price rigidity.
Cartel model. Firms agree to behave as one monopoly. For two identical firms with P = 100 − Q and MC = 20, MR = MC gives total Q = 40 and P = 60. Each makes 20 units and earns (60 − 20) × 20 = 800, joint profit 1,600.
Independent price-taking competition would drive profit to zero.
Instability (Figure 5.4b). If A secretly makes 30 while B keeps to 20, then Q = 50 and P = 50: A earns 900 and B only 600. If both cheat with 30, then Q = 60 and P = 40 and each earns 600.
Cheating is the best reply to either choice, yet both lose compared with 800 each. This is the prisoner's dilemma, and it is why cartels need enforcement and are banned by competition law in many countries.
| Model | Key idea | Outcome |
|---|---|---|
| Kinked demand | rivals copy cuts, ignore rises | stable price |
| Cartel | joint profit maximisation | monopoly price, unstable |
| Price leadership | one firm sets, others follow | tacit collusion |
Conclusion. Oligopoly lies between competition and monopoly: prices are rigid, rivalry is shown in advertising, and collusion is tempting but fragile.